Machining Aerospace Metal
Anyone who has walked the engineering clusters of Peenya or Coimbatore, or the vendor aisles at Aero India, knows that Indian precision machining has quietly become world-class. Our Tier-2 and Tier-3 shops hold AS9100 certification standards, deliver against Airbus and Boeing offsets, and feed HAL, DRDO and ISRO programs. The bottleneck in Indian aerospace manufacturing is no longer skill or equipment. It is the metal itself.
Machining Complexity
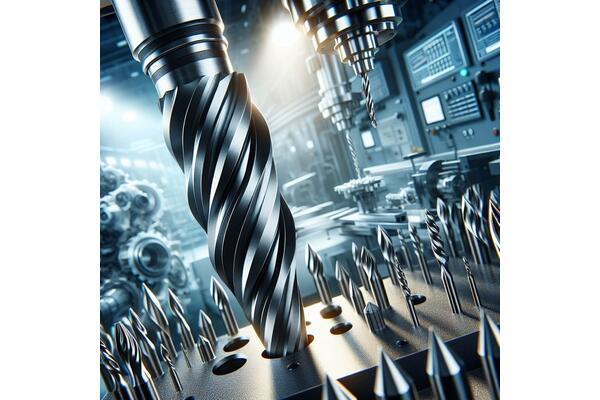
The difficulty is not one of operator skill. Titanium and nickel superalloys are built to hold their strength at temperatures that would destroy ordinary steel, and that very virtue makes them difficult to machine. In a well-behaved material, most of the heat generated leaves with the chip; in titanium, which conducts heat poorly, it has nowhere to go but into the tool. It is the cutting edge, not the workpiece, that suffers.
Everything else follows. These alloys work-harden under the tool, so a light or rubbing pass leaves a hardened skin the next pass must fight through. At high temperatures, chemical affinity can cause hot chips to weld onto the rake face, forming a built-up edge that alters the cut before breaking away and carrying part of the insert with it. Abrasive particles grind at the flank, and notch wear at the depth-of-cut line can finish an insert in a single pass.
What It Costs on the Shop Floor
The consequences are unforgiving. Cutting speeds are a fraction of those for steel, so cycle times stretch and machine-hour costing goes out of the window. Inserts must be changed on a predicted schedule rather than when they look worn, because a superalloy tool does not fail gracefully. Rigid fixturing and high-pressure coolant are requirements, not refinements.
The stakes are higher here than in Toulouse or Seattle. Buy-to-fly ratios on machined structures are poor, and a scrapped part is lost imported metal, replaced only after months and in foreign exchange. The discipline to cut these alloys well is worth building only if the material arrives reliably.
The Supply Question
Reliable supply is the question. India imports roughly 70 percent of its aerospace-grade raw material, for structural reasons. We hold some of the world’s largest reserves of titanium-bearing minerals, yet domestic sponge comes from one producer, Kerala Minerals and Metals Ltd (KMML), capped at 500 tonne a year since 2011. Mishra Dhatu Nigam (MIDHANI) Hyderabad was until recently our only mill for aerospace-grade titanium and nickel superalloys; PTC Industries commissioned the first private vacuum arc remelting furnace in January 2025. For many superalloy grades MIDHANI still stands alone, and it must itself import nickel, cobalt and tungsten, keeping a strategic ‘metal bank’ to hold production steady.
Certification compounds the scarcity: clearing a locally melted batch of alloy as airworthy through CEMILAC takes years, so capacity cannot become supply on demand. Mills prefer bulk orders, and Tier-3 unit needing smaller amounts has to turn to specialty importers, adding to the costs.
For Airbus and Boeing work, a further layer applies.
Every batch must trace back to a mill on the OEM’s Approved Vendor List, and flight-critical heat treatment and testing must be NADCAP-accredited.
Until this month, India had no independent laboratory so accredited: TCR Engineering’s units in Navi Mumbai and Vadodara received the first approval in August 2026. Before that, specimens travelled to America or Singapore.
What Needs to Change
The first movers exist: a private melt shop, an accredited laboratory, clearances for MIDHANI material from GE Aerospace. What is lacking is a reliable supply chain. The Ministry of Defence has begun naming raw materials as well as components; the sixth indigenization list, notified this month, includes them. But a list bans an import; it does not melt an ingot. And it binds defence procurement only, leaving commercial work to fend for itself. Three things need money: sponge and melt capacity, more accredited laboratories, and service centers willing to sell small lots to small shops.
Demand is not the constraint. Indian carriers have placed some of the largest aircraft orders in history, and AMCA will need alloys we cannot presently melt at scale. The work will come; whether the value stays here is another matter. A supplier base that machines imported material earns the conversion margin and little else. It remains a capacity option rather than a partner designed in from the start. Material capability changes that and cannot be improvised once the order arrives — which is the argument for beginning now.
 |
NIKHIL NAYAK |
 Facebook
.png) Twitter
 Linkedin
 Subscribe